The SMR boom will soon go bust
by Ben Kritz, 3 Nov 25, https://www.msn.com/en-ph/technology/general/the-smr-boom-will-soon-go-bust/ar-AA1PJi1U
ONE sign that the excessively hyped concept of small modular reactors (SMRs) is now living on borrowed time is the lack of enthusiasm in the outlook from energy market analysts, whether they are individuals such as Leonard Hyman, William Tilles and Vaclav Smil, or big firms such as JP Morgan and Jones Lang LaSalle. None of them are optimistic that the sector will be productive before the middle of next decade, and the more critical ones are already predicting that it will never be, and that the “SMR bubble” will burst before the end of this one. My frequent readers will already know that I stand firmly with the latter view; basic market logic, in fact, makes any other view impossible.
In a recent commentary for Oil Price.com, one of the rather large number of online energy market news and analysis outlets, Hyman and Tilles predicted that the SMR bubble will burst in 2029. They based this on the reasonable observation that power supply forecasts are typically done on a three- to five-year timeframe. The fleet of SMRs that are currently expected to be in service between 2030 and 2035 simply will not be there, so energy planners will, at a minimum, omit them from the next planning window, and might decide to forget about them entirely. Deals will dry up, investors will dump their stocks or stop putting venture capital into SMR developers, and those developers will find themselves bankrupt.
That is an entirely plausible and perhaps even likely scenario, but the SMR bubble may burst much sooner than that, perhaps even as soon as next year, because of the existence of the other tech bubble, artificial intelligence, or AI, an acronym that in my mind sounds like “as if.” The topic of the AI bubble is an enormous can of worms, too complex to discuss right now, but the basic problem with it that is relevant to the SMR sector is that AI developers need a great deal of energy immediately. It has reached a point where AI-related data centers are described in terms of their energy requirements — in gigawatt increments — rather than their processing capacity. The availability of power determines whether or not a data center can be built; if the power is not already available, it must be within the relatively short time it will take to complete the data center’s construction.
Even if SMRs were readily available, their costs would discourage customers; AI developers are not too concerned with energy costs now, but they will be as their needs to start actually generating a profit become more acute. On a per-unit basis, SMRs are and are likely to always be more expensive than conventional, gigawatt-scale nuclear plants, and for that matter, most other power supply options. Hyman and Tilles estimate that on a per-unit cost basis (e.g., cost per megawatt-hour or gigawatt-hour), SMRs will be about 30 percent higher than the most efficient available gigawatt-scale large nuclear plants. Being smaller, SMRs would — hypothetically, as they do not actually exist yet — certainly cost less up front than large nuclear or conventionally fueled power plants, but their electricity would cost much more in the long run. That might not be an issue in some applications, but it certainly would if SMRs were intended to supply electricity to a national or regional grid.
Some analyses point out that some early adopters of SMRs, that is, customers who have put down money or otherwise promised to order one or more SMR units if and when they become available, may not be particularly price-sensitive; for example, military customers, governments taking responsibility for supplying electricity to remote areas, or some industrial customers. However, they would still be tripped up by the fragmented nature of the SMR sector, which was caused by the “tech bro” mindset of ignoring almost 70 years of experience in nuclear development and trying to reinvent the wheel.
JP Morgan’s 2025 energy report noted that there are only three SMRs in existence, with one additional one under construction; there is one in China, two in Russia, and the one not yet completed is in Argentina. All of them had construction timelines of three to four years, but took 12 years to complete; or in Argentina’s case, 12 years and counting. Argentina’s project has had cost overruns of 700 percent so far, while China and Russia’s projects were 300 percent and 400 percent over budget, respectively.
These are all essentially one-off, first-of-a-kind units, so some of these problems are to be expected, such as regulatory delays, design and manufacturing inefficiencies, and challenges from building supply chains from scratch. These problems would be resolved over time, except that there are literally hundreds of different SMR designs all competing for the same finite, niche-application market.
If the SMR developers listened to the engineers and policymakers who built up nuclear energy sectors that took advantage of economies of scale by standardizing a few designs and distributing the workload, they might get somewhere. That is not happening; potential customers, whether they have power cost concerns or not, are reluctant to jump in because it is not at all certain which SMRs will survive the competition. They might be willing to experiment to see if one design or another actually works — that is why the Chinese and Russian SMRs exist — but the fragmented SMR sector prevents them from trying more than one and making comparisons, at least not in a timely or financially rational manner.
I think the bubble begins to burst this coming year. The timeframe for construction to startup in most SMR pitches is four years. That’s entirely too optimistic, of course, but even if it is taken at face value, once we get a few months into 2026 without any tangible development happening, everyone will catch on that there won’t be any SMRs by 2030, and interest will turn elsewhere. It already is, among the data center sector, as was explained above.
The Silicon Thirst: When Data Drinks the World Dry

4 November 2025 Andrew Klein, https://theaimn.net/the-silicon-thirst-when-data-drinks-the-world-dry/
We live in an age of digital miracles, where intelligence is artificial and clouds are not in the sky, but in warehouses. Yet, this ethereal realm has a staggering physical appetite, one that is quietly draining the planet of its most vital resource: water.
The numbers are not just statistics; they are a prognosis.
- A single data centre can consume 1 to 5 million gallons of water per day – the equivalent of a small city.
- Training a single advanced AI model can gulp down 185,000 gallons of fresh, clean water, used to cool the furious processors dreaming of a digital future.
- By 2027, the water footprint of the AI sector alone could reach 4.2 billion cubic metres, a thirst that begins to compete with the needs of nations.
This is not progress. It is a profound and suicidal miscalculation.
Efficiency for What?
The technology giants speak of “efficiency,” but it is a narrow, self-serving metric. It is the efficiency of a faster loading time, a more intrusive advertisement, a more powerful algorithm for predicting our desires. But by what possible measure is it “efficient” to exchange a million gallons of drinking water for a fractional improvement in computational speed?
This is the logic of a parasite that has forgotten its host is mortal. It is the logic of a civilisation that will meticulously optimise a virtual world while making the physical one uninhabitable.
The Path of the Steward: A Call for Conscious Calculation
The solution is not to abandon technology, but to re-forge it in the image of stewardship. We must demand a new calculus, where the true cost of every byte and algorithm is accounted for. This requires:
- A Radical Shift in Cooling: The era of guzzling pristine freshwater must end. Investment must be urgently directed toward air-assisted liquid cooling, the use of recycled or saltwater, and the strategic placement of data centres in colder climates to drastically reduce their environmental burden.
- Transparency and Accountability: The water footprint of digital services must be made as visible as their price tag. Consumers and regulators have a right to know the true ecological cost of their cloud storage and AI queries.
- Licensing to Operate: A social license to operate in the 21st century must be contingent on water neutrality and a demonstrable positive environmental impact. Profit cannot be the sole metric of success when the very habitability of our home is at stake.
The choice is no longer between technology and nature. The choice is between a technology that devours its own foundation, and a technology that exists in harmony with it.
The silicon world is thirsty. But the thirst of children, of farms, of ecosystems, must come first.
The Risky Movement to Make America Nuclear Again

As the licensing team dug in, Oklo couldn’t provide the supporting analysis for many of its basic safety assumptions
As the licensing team dug in, Oklo couldn’t provide the supporting analysis for many of its basic safety assumptions
A Silicon Valley startup called Oklo is leading the charge to bring nuclear power back to the US with small reactors. Its backers have wealth and political connections that could undermine nuclear safety.
Bloomberg, By Michael Riley,
When Oklo Inc., a nuclear power startup, applied in 2020 to operate its first reactor, the company rested largely on outsize ambition. Its MIT-educated co-founders, a married couple named Jacob and Caroline DeWitte, lived in a mobile home park in Mountain View, California, in space 38. Oklo, which had only 20 full-time employees, wanted to build small reactors across the country, transforming the way towns and industries are powered. To realize that dream, it needed the US Nuclear Regulatory Commission to say the company’s design was safe.
Two years later, Oklo had failed to pass even the first step of the approval process. In 2022, after months of frustrating back and forth, the NRC concluded that the company didn’t provide verifiable answers to the most basic safety questions. The regulator denied the application. A former senior agency official, who spoke on the condition of anonymity, says Oklo “is probably the worst applicant the NRC has ever had.”
For Jake DeWitte, the denial was maddening. He still grows visibly agitated when recounting the moment. “They completely screwed up,” he says. By the end, Caroline says, the agency “became kind of malicious, frankly.”
In 2025, Oklo’s reactor design is still unlicensed. But, in a sign of how radically the safety landscape has changed for nuclear power, the company’s business promise seems bright. Oklo went public last year and now has a market value hovering around $20 billion. In May, Jake was in the White House when President Donald Trump signed four executive orders designed to herald a nuclear renaissance. “It’s a brilliant industry,” Trump said, DeWitte at his side.
The startup’s backers long had a Plan B: If Oklo couldn’t win approval from the agency charged with protecting the public from nuclear accidents, they would, essentially, go after the regulator, in much the way Uber Technologies Inc. and other Silicon Valley startups have obliterated regulatory roadblocks. One of the architects of Oklo’s attack-the-regulator strategy is a law professor-turned-venture capitalist with ties to the Koch empire. He says the public shouldn’t be worried.
The revival of nuclear power in the US has been predicted countless times since President Dwight D. Eisenhower’s Atoms for Peace program rose from the ashes of Hiroshima and Nagasaki. This version, though, is something never before seen. Rather than huge power stations built by engineering companies for giant utilities, a new breed of nuclear startup wants to commercialize reactors, some so small they could be carried on semitrucks, so mighty they could power the hungriest of artificial intelligence data centers. Not one of these so-called advanced reactors has yet to be built in the US, but their promise has touched off a dealmaking frenzy, with backing from tech giants including Amazon.com, Google, Meta Platforms and Microsoft. The US Department of Energy has announced a goal of having at least three of these reactors switched on by July 4 of next year.
Oklo’s power and influence in the MAGA era have let it seize the political moment
Oklo isn’t the most obvious company of the two dozen or so newcomers to have broken through as a front-runner. Bill Gates’ TerraPower LLC has been trying to develop an advanced reactor for almost two decades. Kairos Power LLC, backed by Google, has made quick progress through the government’s licensing process.
But Oklo’s power and influence in the MAGA era have let it seize the political moment. The company is backed by some of Silicon Valley’s most important leaders, including Sam Altman, co-founder of OpenAI. A former board member is now Trump’s secretary of energy. Critically, Oklo has capitalized on the deregulatory fever gripping Washington. The NRC, which became a target of Trump’s Department of Government Efficiency, or DOGE, has lost at least 195 staff since January, and efforts to strip the agency of key powers are underway.
For a half-century, the NRC has been the watchdog of an industry built on some of the most dangerous technologies ever known. Yet Oklo and its backers say that its reactors will be so small and safe, little NRC oversight is needed.
Even a year ago, this proposition would have been absurd. Experts say advanced reactors are indeed safer in some respects: Because they’re a third or less the size of traditional reactors and aren’t cooled by water circulating under immense pressure, a serious accident is less likely to spread radioactive debris across a major populace. But for anyone nearby—workers operating the plant, say, or soldiers on a military base powered by one—the dangers could be substantial.
“All these nuke bros who know nothing about operating a reactor, they just want a free pass,” says Allison Macfarlane, former chairman of the NRC. “They can have their free pass, but then they will have an accident.”…………………………………………………………………………………………………………………………………………………………………………….
Transatomic’s collapse left venture capital’s tech titans looking for a new standard bearer in their drive to disrupt nuclear power.
In January 2018, some of the country’s richest and most powerful descended on the desert resort town of Indian Wells, California, for three days of hobnobbing over canapés and golf. They had come for the annual donor retreat established by the chemicals-and-refining billionaires Charles and David Koch; before the weekend was out, they had pledged to spend more than $400 million to support the Kochs’ political influence operation, which counted governors, senators and state legislative leaders as foot soldiers.
Among those attending was a law professor-turned-venture capitalist named Salen Churi. Co-founder of a new Koch-backed VC firm called Trust Ventures, Churi explained the firm’s novel strategy as he worked the target-rich room for potential investors: identify startups facing steep regulatory challenges; solve them through litigation, advocacy and political influence; and then watch the profits roll in.
“Imagine a startup able to tap into the know-how of Koch from Day 1,” Churi said, according to news coverage of his presentation. The company’s first big investment, in mid-2018, was in Oklo. (Another investor in 2018 was Rothrock; he invested in Oklo around the same time that Transatomic folded.)……………………………………………..
…………………………………………………….. Eighty feet high and fashioned from 1-inch-thick steel plating, the shiny silver dome of the Experimental Breeder Reactor-II rises from the eastern Idaho sagebrush like a lost artifact of the Atomic Age. At one point, 52 test reactors of various types operated on this stretch of high desert. It’s the home of the Idaho National Laboratory, formerly known as Argonne-West, where nuclear power was born.
Nowadays, scientists, government officials, tourists and others have turned this site into a pilgrimage. (The filmmaker Oliver Stone paid a visit not long ago.) Some of them come to see or learn from the Experimental Breeder Reactor-II, or EBR-II, a sodium fast reactor that is considered by many to be the lab’s most successful attempt to revolutionize the way nuclear energy is created.
There’s a renewed belief that this long-forgotten technology—EBR-II was built six decades ago and decommissioned in the mid-1990s—holds the keys to a safer, more efficient nuclear industry. Adherents argue that the technology, unlike other reactors, is “passively safe”—so safe that in even some of the worst accident scenarios, a sodium fast reactor would shut down without human intervention.
Not far from the massive silver dome is a patch of government land where the DeWittes have staked their future. Little more than a sign and a couple of porta potties stashed amid the juniper bushes, this is where the two are planning to build Oklo’s reactor, Aurora, which they’ve described as a more modern version of the EBR-II. They have vowed that their reactor will share the same inherent safety characteristics.
Edwin Lyman, a physicist and director of nuclear power safety with the Union of Concerned Scientists, says the assumption that reactors like EBR-II are “passively safe” is misguided. “It’s gaslighting,” he says. Sodium fast reactors are notoriously difficult to operate, which accounts for the technology’s long history of accidents and meltdowns. Sodium leaks can create fires that spray a toxic sodium-oxide aerosol into the air. If the coolant comes into contact with water, hydrogen explosions can result in both the reactor itself and the power generation plant. And compared with light-water reactors, fast reactors leak neutrons that need extensive shielding to make them safe. “If something goes wrong, the potential for a Chernobyl-like escalating event is actually much higher than it is with light-water reactors,” Lyman says.
When Oklo submitted its first application to the NRC in 2020, the agency was under pressure from Congress and the industry to show it could license new reactors more efficiently. The agency’s licensing team was eager to begin what it called a Phase 1 review—essentially checking that the application is complete enough to move to a more rigorous scientific and safety evaluation. With an experienced company, Phase 1 usually takes about two months. “We thought we could get Oklo to that point in about six months,” says a former agency official familiar with the company’s application, who asked for anonymity to talk openly about the company’s application.
Major sticking points soon emerged. The company declared that, based on its extensive calculations, Aurora was one of the safest nuclear reactors in the world and there was no plausible accident that would result in a release of radiation into the environment. Yet the NRC staff identified important scenarios that Oklo didn’t appear to consider: What if undulating pipes from a sudden leak wrecked key systems? What if the seals of the reactor capsule failed, creating a pathway for radiation to reach the outside? The regulators also asked about the risk of flooding inside the reactor capsule, which the NRC said “may represent a potential criticality issue.” Nuclear experts say that’s a technical way of saying that the agency was worried about the possibility of an uncontrolled fission uncontrolled fission event, which could result in a dangerous steam explosion inside the reactor vessel.
As the licensing team dug in, Oklo couldn’t provide the supporting analysis for many of its basic safety assumptions, according to four officials who spoke to Businessweek about the application, as well as public NRC documents. In some cases, supporting files the company claimed to have were not available when the NRC tried to examine them, one official says.
“We needed the evidence that this reactor could be built and operated safely, and it just wasn’t forthcoming,” says one of the four officials.
Finally, in January 2022, the NRC denied Oklo’s application. By that point, the company had raised more than $25 million, and its dream of mass producing small nuclear reactors had seemed in reach. But at the NRC, the company never made it beyond Phase 1.
In a flashy video posted on YouTube last year, the DeWittes, clad in jeans, stroll across the high prairie near the Idaho National Laboratory. They’re introduced by a narrator whose tone mixes soothing and serious. “Meet the husband-and-wife engineering duo that discovered a game-changing technology buried in a government lab in Idaho,” the narrator says.
The six-and-a-half-minute video was published on the YouTube channel of a Utah-based organization called the Abundance Institute, identified on its website as “a mission-driven nonprofit focused on creating a space for emerging technologies.” In contrast to other pro-nuclear outfits including Third Way and the Breakthrough Institute, the Abundance Institute has been ferocious in its criticism of the NRC. In January its CEO penned an op-ed in the Wall Street Journal that labeled the regulator “lawless,” then followed up with social media posts declaring that it was time to abolish the agency.
What the videos and op-eds don’t disclose is that the Abundance Institute is Churi’s brainchild. He’s a co-founder and is listed as the institute’s treasurer in papers filed with the Utah secretary of state’s office. The same papers list, as an institute director, Derek Johnson. He’s a central player on the Kochs’ national political team and executive vice president at the Kochs’ umbrella group, Stand Together, which also published the Oklo video……………….
“The people who get one-cent electricity from nuclear don’t exist yet because we can’t give it to them yet,” Churi says. “We wanted to be the lobbyist for companies that don’t exist yet and for consumers who haven’t gotten the benefit of those technologies yet.”
The institute is so intertwined with the Koch family’s famed influence network that it’s hard to distinguish between the two. Many of its key employees, including the CEO, come from the Center for Growth and Opportunity at Utah State University, sometimes called “Koch U of the West,” a reference to a similar Koch-funded outfit at George Mason University in Virginia. Churi listed CGO’s offices as his address in papers that the Abundance Institute filed with the state. (Christopher Koopman, the institute’s CEO, called that a “clerical error.”)
Emails and other documents obtained through public records requests show that the Abundance Institute effectively serves as a front for Churi’s attack-the-regulator mission. As his team dissected federal regulations, Churi spotted language that might offer an opening. In 1956 the Atomic Energy Commission determined that because any apparatus designed to carry out a nuclear fission chain reaction can affect the health and safety of the public, it needs a federal license. Nuclear startups could argue that their reactors are so small and safe that they don’t present any risk to the public—and therefore fall outside federal jurisdiction. It was a long-shot position on the science, but the right court might just buy it. Churi and the team went to work.
They began looking for a nuclear startup willing to be the public face of the challenge. And, because a major goal of the lawsuit was to shift oversight of small nuclear reactors from the NRC to the states, they recruited state attorneys general as lead plaintiffs.
For the first, they linked up with Bret Kugelmass, founder and CEO of Last Energy Inc., which boasts a reactor design using off-the-shelf components. Kugelmass has little to no experience in nuclear engineering—his last company used drones to map farmland—but he has a popular energy podcast and is close to the MAGA movement. One Oklo investor called him “like Elon in his take-no-prisoners approach to getting stuff done.”
For the second, Churi and the Abundance Institute targeted officials in Texas and Utah, two states where Churi spends much of his time and knows, he says, “a lot of folks who work in both politics and the AG offices.” In Utah, the Abundance Institute served as a conduit to those officials, leveraging the Koch family’s political clout as well.
According to emails obtained by Businessweek through a public records request, Utah Senate President J. Stuart Adams and an aide met with Abundance Institute staff in the fall of 2024. Afterward, the aide wrote Utah Chief Deputy Attorney General Dan Burton, saying the institute was “gathering clients for a nationwide lawsuit against the NRC.” Then he added, “We think it would be worth you/the AG’s time to explore their proposal and determine whether it makes sense for Utah to join.”…………………………………………………..
As the team prepared to file its federal lawsuit, a second and potentially more direct path to gutting the NRC opened up. The country had just voted to send Donald Trump back to the White House.
In February 2023, Jake DeWitte flew spur of the moment to Denver in hopes of buying a Kia Telluride he’d found online. His trip changed the future of the company.
Denver happened to be the home base for Chris Wright, founder and CEO of the second-largest fracking company in North America, Liberty Energy Inc. …………………………….
The timing was propitious, and not only for Oklo. The buy-in—structured as a $10 million strategic investment by Liberty—was finalized just weeks before an announcement in June that one of Altman’s companies, a special purpose acquisition company (SPAC), would take Oklo public. Jake says Oklo extended its last VC round to allow Liberty to get in under the wire, making Liberty one of the last early investors before Oklo began trading on the New York Stock Exchange the following year, with an initial valuation of $850 million……………………………………………..
In his first departmental directive, issued in early February, Wright declared that “the long-awaited American nuclear renaissance must launch during President Trump’s administration.” The directive said that the Energy Department would work to enable the “rapid deployment” of next-generation nuclear technology.
Meanwhile, Trump began a slash-and-burn campaign to hollow out federal regulators, including nominally independent agencies such as the Securities and Exchange Commission and the National Labor Relations Board. By April, drafts of four executive orders targeting the regulation of nuclear energy began circulating…………………………………………………………………..
One person who did get input on the orders, by her own account, was Isabelle Boemeke, a Brazilian model and self-described nuclear energy influencer who goes by the moniker Isodope. Author of a book on nuclear power titled Rad Future, Boemeke is famous for mobilizing her social media followers in a successful drive to keep the Diablo Canyon nuclear power plant north of Los Angeles operating beyond its scheduled retirement. She’s also the spouse of Joe Gebbia, one of the founders of Airbnb and a prominent DOGE figure………………………………………….
……………………………………….. The federal lawsuit against the NRC was filed in December, with Texas and Utah as lead plaintiffs. By March the NRC had responded with a strongly worded motion asking the court to dismiss the lawsuit.
Behind the scenes, something very different was happening. At the end of April, the plaintiffs’ lead lawyer, a partner at the boutique firm Boyden Gray named Michael Buschbacher, emailed his colleagues with good news. The NRC was ready to discuss a settlement and potentially agree to the plaintiffs’ biggest demand: the initiation of a rule-making process with the goal of exempting some small nuclear reactors from traditional NRC oversight and handing it to state agencies instead.
Meanwhile, the startups have another pathway to get their reactors to market quickly. In August, the Department of Energy announced a pilot program with the goal of deploying at least three untested reactors by next July 4, to coincide with the 250th anniversary of the signing of the Declaration of Independence. Oklo plans to license its first Aurora reactor through this program, the company says, although its reactor won’t be ready by then.
The company says it still plans to license future reactors via the NRC, but it will benefit from a radically changed agency. The executive orders signed in May push the agency to approve new reactor licenses within 18 months and to further expedite approval for any power plants already OK’d by the Defense Department or the Energy Department, two entities that have never licensed a commercial reactor. The NRC’s Advisory Committee on Reactor Safeguards, a panel of experts who weigh in on safety issues posed by new designs, had its remit pared back to the “minimum necessary” required by law.
………………………..both the NRC’s general counsel and its executive director of operations were pushed out, two people familiar with those moves said. Trump fired one commissioner in mid-June, and a second resigned a few weeks later.
………………………………………… At a recent meeting with NRC employees, DOGE representatives handed out black ballcaps emblazoned with “Make Nuclear Great Again” alongside the logo for another nuclear startup, Valar Atomics, according to a former agency official familiar with the meeting……………………………………………………………………………
By this summer, it was clear that Churi and his team had won, and not only for Oklo. Their efforts have created an opening that other nuclear startups—and their Silicon Valley backers—can now draft behind. One of those companies, Deep Fission, plans to operate small nuclear reactors a mile underground, a concept that’s never been tried anywhere. Valar Atomics, which joined the lawsuit against the NRC in April, claims on its website that you can safely hold spent nuclear fuel from its reactor for five minutes in the palm of your hand—something that nuclear experts say would quickly kill anyone who tries it. Both companies were also recently chosen for the Energy Department’s new accelerated licensing program………………….. https://www.bloomberg.com/news/features/2025-10-30/silicon-valley-s-risky-plan-to-revive-nuclear-power-in-america?embedded-checkout=true
Busting the Spin on Small Modular Reactors – the CATO Institute !
At the heart of the case for SMRs is the claim that being smaller, they will be cheaper, quicker, and easier to build and easier to site. While this argument might appear plausible, it is not supported by any evidence.
the output of the 470MW Rolls Royce SMR is about the same size as that of the Fukushima Daiichi 1 reactor that melted down in 2011.
a large PWR or BWR will create less waste than the same capacity of SMRs.
an operating reactor requires few permanent employees, and those workers typically have highly specific skills unlikely to be found among the local population. …………………..The number of factory jobs that are created is likely to be small and will mostly not be in the country buying the reactor.
The CATO Institute, Fall 2025 • Regulation
……………………………………………………………………Instead of another round of large nuclear plants, one of the focal points of the new renaissance is Small Modular Reactors (SMRs). The International Atomic Energy Agency (IAEA) defines SMRs as having an electrical output of 30MW–300MW.
Among their ostensible virtues:
- They are cheaper and easier to build and so are less prone to cost and time overruns, making them easier to finance.
- They are safer; for example, some are said to be meltdown-proof and “walk-away safe.”
- They produce less waste (per kW of capacity) than large reactors.
- Being smaller, there will be less opposition to their siting.
- They will create large numbers of new jobs.
SMR proponents give the impression that large numbers of the units are being ordered around the world. These claims are unproven or misleading or simply wrong. No current SMR design is under construction, much less operating, so these claims—notably those on cost and construction time—are unproven and no more than marketing hype. There are two SMR-sized units under construction, in China and Russia, but they are prototypes or one-offs. The true SMR project nearest to construction start (as defined by pouring of first structural concrete) is the Darlington project for Ontario, Canada, for up to four GE–Hitachi BWRX–300s (explained below). The Ontario government approved construction of the first reactor in May 2025.
No SMR design that is expected to be offered as a commercial reactor has completed a full safety review by an experienced and credible regulator. The Canadian Nuclear Safety Commission will examine the design during the Darlington construction phase rather than before construction starts. Until a comprehensive safety review is successfully completed, it will not be known if the design is licensable or what the costs will be.
The designs most likely to progress to commercial availability are those based on the PWR and BWR designs in LWR large reactors. There are 65 years of operating experience with these types of reactors, so there is a reasonable expectation that SMR LWRs could be reliable, if not necessarily economic, sources of power.
Many designs for these units are said to be under development, but only a handful have progressed beyond the conceptual stage and are being offered by firms with the credibility to deliver a facility expected to cost several billion dollars. The main options are the GE–Hitachi BWRX–300, the Holtec SMR300, the Rolls Royce SMR, and the Westinghouse AP300. Below are overviews of these four designs, along with some other possibilities.

GE–Hitachi BWRX–300 / General Electric, along with Westinghouse, has by far the longest and most extensive experience in designing and supplying nuclear power reactors. The 300MW BWR is based on its ESBWR 1,500MW reactor design. Although the ESBWR completed US Nuclear Regulatory Commission (NRC) safety review in 2014, GE–Hitachi has won no orders, and it currently does not appear to be actively marketing the unit.
Like the ESBWR, the BWRX–300 relies heavily on passive safety features. GE–Hitachi received an order for up to four of the reactors to be built at the Darlington site. It has completed a pre-licensing review in Canada and a construction license has been given. A detailed review of the design will be carried out during construction prior to an operating license being granted.
The BWRX–300 was one of four designs shortlisted by Great British Energy–Nuclear (GBE–N), with the UK government-owned energy organization expected to choose two designs for installation in Scotland and England. But in June 2025, GBE–N announced only that it had selected the Rolls Royce SMR design, discussed below.
The UK Office of Nuclear Regulation (ONR) is carrying out its Generic Design Assessment (GDA) on the BWRX–300, and it completed the first of the three stages of the GDA in December 2024 (primarily information exchange). GE–Hitachi has only committed to carry out the first two stages of review, and is unlikely to undertake the third stage given that it was not selected by GBE–N.

Holtec SMR 300 / Holtec has a long history in the spent-fuel handling and plant decommissioning sectors of the nuclear power industry, but not as a reactor designer and vendor. It launched its PWR SMR design in 2010, initially proposing a 160MW reactor. The unit is designed to be housed deep underground, relying on passive safety (claimed to be “walk-away safe”). In 2023, Holtec doubled the thermal output of the plant and renamed it SMR 300. It is not willing to say when it decided to make that change or why, but the most likely explanation is to gain scale economies.
Its main sales prospect is to initially build two reactors at Holtec’s Palisades site in Michigan, adjacent to an 801MW reactor Holtec owns and is preparing to reopen after it was idled in 2022.
It was one of the four designs shortlisted by GBE–N. ONR is carrying out its GDA on the Holtec SMR 300, but like GE–Hitachi, Holtec is unlikely to carry out the third stage given that it was not selected by GBE–N.
Rolls Royce SMR / Rolls Royce has a long history of supplying nuclear submarine reactors based on US designs. It is not clear how well this equips the firm to design and supply land-based power reactors. Its design is a 470MW PWR, making it significantly larger than the top of the IAEA’s range for SMRs.
Unlike the other three designs, it is much more conventional, not relying so much on passive safety and not housed underground. Its main sales prospects are in the UK and the Czech Republic. In the UK, it submitted a Final Tender to GBE–N in April 2025 and was selected by the government. ONR is carrying out its GDA on the reactor. It completed the second of the three stages in July 2024, and the third stage is expected to be completed in 2026.
Rolls Royce signed a deal in October 2024 with the Czech utility CEZ for it to help develop the design. It expects that three initial orders will be placed for the Czech Republic, with them coming online in 2034–2037. In February 2025, there were reports of tension between Rolls Royce and CEZ—in particular, over how much local Czech content there would be in reactor orders.
Westinghouse AP300 / Westinghouse has supplied substantially more power reactors worldwide than any other vendor. Its SMR design, the AP300 PWR, was launched well after its competitors in May 2023 and is based on the AP1000 large reactor design. It relies on passive safety.
In the UK, it applied for the design to undergo a GDA. In August 2024, it passed the government’s “readiness” test and was allowed to move on to a GDA. However, by December 2024, no funding package to pay for this process (expected to be funded by the vendor) had been agreed upon, and Westinghouse asked ONR to defer the start of the GDA. By May 2025, the GDA had not started, and there is no indication whether Westinghouse expects to proceed.
It chose not to respond to GBE–N’s Invitation to Submit Final Tenders for its project discussed above. Westinghouse has not commented on its decision not to proceed with the GDA or its decision not to submit a Final Tender to GBE–N. It may be that it has halted work until there is more concrete buyer interest in the design. If the design is not pursued, this would be the second time Westinghouse has carried out development work on an SMR design only to abandon it before it had won any orders, the previous attempt being halted in 2014.
Other possibilities / Besides those reactors, the French nuclear engineering firm Framatome began developing a design, Nuward, in 2019. It abandoned the design in the summer of 2024 in favor of a more conventional layout, and there is no timeframe for when this new design might be available.
A US firm, NuScale, has a design that has been under development since 2005. It started out as a 35MW PWR, then expanded to 40MW, 50MW, 60MW, and finally 77MW. The design, which successfully completed NRC review in May 2025, is “integrated” with all components housed within the reactor containment and would be built underground. It was designed to be built in clusters of 12 reactors, but the 77MW version is now also offered in clusters of four and six reactors. It appeared to have won an order in 2015 from Utah Associated Municipal Power (UAMPS) for a cluster of 12 reactors of 50MW, which then evolved into a cluster of six 77MW reactors, but the project was abandoned in December 2023 because of sharply escalating cost.
Arguments for SMRs / At the heart of the case for SMRs is the claim that being smaller, they will be cheaper, quicker, and easier to build and easier to site. While this argument might appear plausible, it is not supported by any evidence. The first reactors from more than 60 years ago were 150 MW or less, and reactors subsequently became larger, increasing in size 10-fold, primarily to gain scale economies. The case for this is clear: A 1,500MW reactor vessel will, all things being equal, be cheaper than ten 150MW reactor vessels. So, SMRs start with a disadvantage compared to large reactors because of the lost scale economies over large designs.
However, there is no clear evidence on why the real cost of large reactors has continuously increased over the history of nuclear power. Is it because of their size or because of how complex the designs have become? If it is complexity, why would SMRs be less complex than large reactors? The most obvious way this could happen is if not all the safety systems added to large reactors over the past 40 years were required for SMRs. Given that the SMRs on offer are not that small, this seems unlikely. For example, the output of the 470MW Rolls Royce SMR is about the same size as that of the Fukushima Daiichi 1 reactor that melted down in 2011.
The history of the Westinghouse AP design reactors illustrates the nuclear industry’s confusing position on reactor size. Its 1989 AP600 design was found to be uneconomic and was scaled up to the AP1000 in 2002, then scaled up again in 2013 to the CAP1400 and, in 2023, scaled down to the AP300.
Safety Many SMR safety claims are based on their use of passive safety measures. The intuitive impression is that because passive safety does not require the operation of an engineered system, it would be cheaper and, because it is passive, it cannot fail (Ramana 2024). Neither assumption is true. Building reactors underground appears likely to increase site work and make it more difficult and expensive. The ESBWR and AP1000 large reactor designs are both heavily reliant on passive safety, yet the ESBWR was too expensive to win any orders and the AP1000 proved very expensive to build in practice. That experience does not support the contention that passive safety will reduce costs. If all the safety systems required for large reactors are required for SMRs, this will adversely affect their economics.
Ease of production The idea that SMRs would emerge in several modules from factories and be transported to the site on the back of trucks, requiring only bolting together at the site, also has an intuitive appeal. However, in practice SMRs are substantial-sized reactors and will inevitably require considerable on-site civil works to provide the foundations and services required.
The narrative of factory production lines conjures an image of a conveyor belt producing multiple identical reactor modules, perhaps similar to automobile production lines producing thousands of cars per year. However, this is not the expected reality. Rolls Royce plans to only produce two reactors per year. Although production lines can be a cheap method of manufacture, they must constantly operate at near capacity to pay off their high fixed costs. If demand is less than planned, the high fixed costs will not be spread across many units of electricity, and if the design changes, the production line will have to be re-tooled. The AP1000 was expected to be built in factory modules, yet this did not prevent all the projects using this design from going far over time and budget.

Waste All things equal, a large PWR or BWR will create less waste than the same capacity of SMRs. Former US NRC chair Allison Macfarlane has said that SMRs would increase the volume and complexity of waste between two- and 30-fold because of such factors as greater neutron leakage.
Jobs Both politicians and nuclear power advocates like to claim a new plant will create many new jobs. But an operating reactor requires few permanent employees, and those workers typically have highly specific skills unlikely to be found among the local population. Nuclear reactors do require large numbers of workers during construction, but they too have specific skills unlikely to be found in the local area, and sometimes these workers have to be recruited from abroad. This is very disruptive to the local area, requiring a large amount of short-term accommodation and facilities.
Moreover, if the promises that SMRs will be cheaper and quicker to build than large reactors are fulfilled, they will create less work and over a shorter period. If factories with production lines are efficient, they will require fewer workers than other manufacturing methods. To minimize costs, the number of factories will have to be minimized, and factories will not be built in most export-country markets. The number of factory jobs that are created is likely to be small and will mostly not be in the country buying the reactor……………………………………………………………………………………………………https://www.cato.org/regulation/fall-2025/next-nuclear-renaissance#small-modular-reactors
Generation IV Nuclear Reactor Designs
The Next Nuclear Renaissance?
CATO Institute, Steve Thomas, Fall 2025 • Regulation,
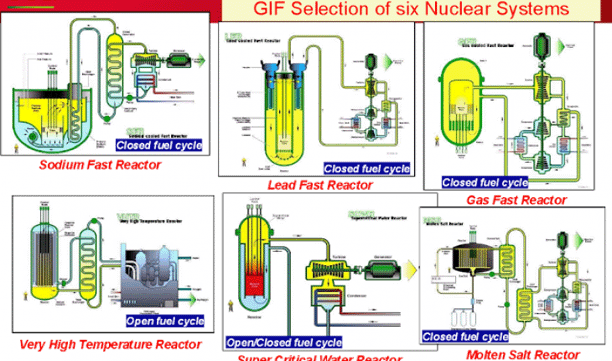
……………………………………………………………………………..Around the time of the previous nuclear renaissance, there was talk of the designs that would succeed Gen III+, so-called Gen IV designs. Gen III+ designs were seen as transitional technologies filling the gap until their long-term successors were developed. The Gen IV International Forum (GIF), an international intergovernmental organization funded by the governments of nearly all the nuclear-using countries, was set up in 2001 to promote development of these designs.
The GIF has stated, “The objectives set for Generation IV designs encompass enhanced fuel efficiency, minimized waste generation, economic competitiveness, and adherence to rigorous safety and proliferation resistance measures.” It identified six designs as the most promising, and these remain its focus. Some are designs that have been pursued since the 1950s and built as prototypes and demonstration plants but never offered as commercial designs. Among these are sodium-cooled fast reactors and high temperature gas-cooled reactors (HTGRs). Some, such as the lead-cooled fast reactor and the molten salt reactor, have been talked about for 50 or more years but never actually built. Others, such as the supercritical-water-cooled reactor and the gas-cooled fast reactor, do not appear to be under serious commercial development. When GIF was created, it expected some of the designs to be commercially available by 2025, but it now does not expect this to happen before 2050.
When the Gen IV initiative began, there was no expectation they would be small or modular. Gen IV designs are now sometimes known as Advanced Modular Reactors (AMRs) in an apparent attempt to profit from the positive press that LWR SMRs are receiving. However, they are very different from LWRs, with different designs and safety requirements, so the claims made for LWR SMRs compared to the large LWR designs are not relevant to AMRs.
There is particular interest in HTGRs because of the hope that they can operate at high temperatures (above 800°C /1,500°F). This would allow a plant to also produce hydrogen more efficiently than conventional electrolysis, providing the plant an additional revenue stream. However, existing HTGRs have only operated at 750°C /1,380°F, much higher than the 375°C /700°F of PWRs but not ideal for producing hydrogen. Increasing the temperature to the levels GIF anticipated originally, 950°C–1,000°C/1,750°F–1,850°F, would require new, expensive materials and would raise significant safety issues. The British government is concentrating its efforts on HTGRs, but it has said, “It is not currently aware of any viable fully commercial proposals for HTGRs that could be deployed in time to make an impact on Net Zero by 2050.” Nevertheless, the UK is still subsidizing development of HTGRs.
Overall, there are high-profile promoters of these Gen IV designs. For example, Microsoft cofounder Bill Gates is investing in sodium-cooled fast reactors through his nuclear innovation firm Terrapower. However, given the 50+ year history of these efforts, it is hard to see why these new companies would succeed now. Few of the more prominent Gen IV designs are being developed by firms with any history of supplying nuclear reactors. At most, Gen IV designs are a long-term hope……………………………. https://www.cato.org/regulation/fall-2025/next-nuclear-renaissance
Generation IV Nuclear Reactor Designs
The Next Nuclear Renaissance?
The CATO Institute, Fall 2025 • Regulation………………………………………………………..Around the time of the previous nuclear renaissance, there was talk of the designs that would succeed Gen III+, so-called Gen IV designs. Gen III+ designs were seen as transitional technologies filling the gap until their long-term successors were developed. The Gen IV International Forum (GIF), an international intergovernmental organization funded by the governments of nearly all the nuclear-using countries, was set up in 2001 to promote development of these designs.
The GIF has stated, “The objectives set for Generation IV designs encompass enhanced fuel efficiency, minimized waste generation, economic competitiveness, and adherence to rigorous safety and proliferation resistance measures.” It identified six designs as the most promising, and these remain its focus. Some are designs that have been pursued since the 1950s and built as prototypes and demonstration plants but never offered as commercial designs. Among these are sodium-cooled fast reactors and high temperature gas-cooled reactors (HTGRs). Some, such as the lead-cooled fast reactor and the molten salt reactor, have been talked about for 50 or more years but never actually built. Others, such as the supercritical-water-cooled reactor and the gas-cooled fast reactor, do not appear to be under serious commercial development. When GIF was created, it expected some of the designs to be commercially available by 2025, but it now does not expect this to happen before 2050.
When the Gen IV initiative began, there was no expectation they would be small or modular. Gen IV designs are now sometimes known as Advanced Modular Reactors (AMRs) in an apparent attempt to profit from the positive press that LWR SMRs are receiving. However, they are very different from LWRs, with different designs and safety requirements, so the claims made for LWR SMRs compared to the large LWR designs are not relevant to AMRs.
There is particular interest in HTGRs because of the hope that they can operate at high temperatures (above 800°C /1,500°F). This would allow a plant to also produce hydrogen more efficiently than conventional electrolysis, providing the plant an additional revenue stream. However, existing HTGRs have only operated at 750°C /1,380°F, much higher than the 375°C /700°F of PWRs but not ideal for producing hydrogen. Increasing the temperature to the levels GIF anticipated originally, 950°C–1,000°C/1,750°F–1,850°F, would require new, expensive materials and would raise significant safety issues. The British government is concentrating its efforts on HTGRs, but it has said, “It is not currently aware of any viable fully commercial proposals for HTGRs that could be deployed in time to make an impact on Net Zero by 2050.” Nevertheless, the UK is still subsidizing development of HTGRs.
Overall, there are high-profile promoters of these Gen IV designs. For example, Microsoft cofounder Bill Gates is investing in sodium-cooled fast reactors through his nuclear innovation firm Terrapower. However, given the 50+ year history of these efforts, it is hard to see why these new companies would succeed now. Few of the more prominent Gen IV designs are being developed by firms with any history of supplying nuclear reactors. At most, Gen IV designs are a long-term hope.
Large Reactors
If we exclude Russia and China (see below), three large reactor designs are currently available, at least in theory: the Westinghouse AP1000, Framatome (formerly known as Areva NP) EPR, and the South Korean KHNPC APR1400. These were all also available at the time of the previous nuclear renaissance, along with the GE–Hitachi ESBWR, but it won no orders and appears to no longer be marketed.
The only work in recent decades on a new design for a large reactor is for a modified version of the EPR, the EPR2. Despite this work starting in 2010, it had not entered detailed design phase as of the start of 2025, and the first reactor using this design is not expected online before about 2038. A new version, Monark, of the Canadian heavy water reactor CANDU has been publicized, but it seems to be at an early stage of development and the only interest in it appears to be from Canada.
The lack of new designs may reflect in part the very high cost of developing a nuclear reactor coupled with the uncertainty whether such research and development will lead to sufficient (if any) sales to recover those costs. For example, in 2023 NuScale stated that work developing its SMR design had cost $1.8 billion. In 2014, Westinghouse estimated it would have to sell 30–50 SMRs to get a return on its R&D investment. The GE–Hitachi ESBWR was carried through to detailed design and successfully completed the US NRC’s design evaluation, but commercial sales failed to materialize, and the vendor appears to no longer offer it. Another factor may be that vendors have exhausted their ideas for improving the economics of large reactors. During the previous renaissance, concepts such as passive safety, modularization, and use of production-line-made components were unable to solve the financial problems associated with large reactor designs (Thomas 2019).
Despite these setbacks, there is growing interest in Europe in large reactors, not just in the well-established markets of France and the UK, but also in countries such as the Czech Republic, Poland, the Netherlands, and Sweden. Below is a more careful look at these units.
Westinghouse AP1000 / The AP1000 (Advanced Passive) 1,100MW PWR won eight orders, four for the United States (two for the Summer plant in South Carolina and two for Vogtle in Georgia) and four for China. The Summer orders were abandoned after four years’ construction, but the others have been completed. The most recent orders were placed in 2010, and all six completed reactors were late and over budget. The Vogtle project took 11 years and cost more than double the forecasted cost. Similarly, the four reactors in China each took about 10 years to complete.
The AP1000 has been chosen by Poland for its first nuclear orders, with construction supposed to begin in 2028 and first power slated for 2036. The design was excluded from the bidding process in the Czech Republic because it “did not meet the necessary conditions.” Westinghouse is competing to win orders in Sweden and the Netherlands, neither of which has made a design choice.
Framatome EPR / The French EPR design is in a sort of limbo at the moment. In 2010, Areva NP acknowledged that the EPR design needed significant modification because of construction problems faced at Olkiluoto 3 (Finland) and Flamanville 3 (France). A modified design has been under development since then, and for the last decade Framatome has claimed it will be ready to order in two or three years. The new EPR2 design has long been expected to be used for follow-on orders from Flamanville 3, leaving only the UK as a customer for the original EPR design, for Hinkley Point C (under construction since 2018) and Sizewell C (ordered this year). In 2021, the French government required EDF to build six EPR2s, one every 18 months, with the first one expected to begin construction in 2026 and be operational in 2035. This timeline cannot be met, and the earliest first power is likely is 2038. Given the record of EPR projects, export customers likely want to see an EPR2 built and in operation before they order one. That would mean the EPR2 design is not an option for new export orders before 2040.
Despite the obvious uncertainties and risks, EDF/Framatome offered a scaled-down version of the EPR2, the EPR1200, to the Czech Republic and Poland. In both cases, Framatome’s bids were unsuccessful. Ordering an EPR1200 ahead of completion of the first EPR2 would have been an extraordinary gamble given that the reactor is an untested, scaled-down version of an untested design.
KHNPC APR 1400 / Korean Hydro and Nuclear Power Company (KHNPC) is a subsidiary of the state-owned monopoly electric utility KEPCO. The design is derived from the American engineering firm Combustion Engineering’s System 80+ design that completed a full safety review by the US NRC in 1997 but has received no orders. Combustion Engineering was absorbed into Westinghouse, and KHNPC purchased a technology license for the design.
In South Korea, six reactors of this design have been completed, the first in 2016, with two under construction as of July 2025. All except one of the completed reactors took more than 10 years to build, and the two under construction are far behind schedule. South Korea’s only reactor export has been four units, all using this design and built in the United Arab Emirates. All four took nine years to build.
KHNPC has acknowledged the design that has been built in South Korea and the UAE lacks features that would be essential for it to be licensed in Europe. Besides, under a recent change to its licensing agreement with Westinghouse, KHNPC is prohibited from marketing the unit in EU countries other than the Czech Republic, and also prohibited in Britain, Ukraine, Japan, and North America. Nevertheless, KHNPC appears confident that a scaled-down version of the APR1400, the APR1000, will be ordered by the Czech Republic. As with the EPR1200, ordering this untested design would be a gamble.
Prospects for large reactors / While the large reactor options look dated and their record is poor, in Europe they appear to have better prospects for orders in the next few years than SMRs. All will depend on a national government risking large amounts of public money to make these projects happen. France and the UK seem determined to follow this path, but other countries, which do not have as much financial strength, may waver when they find the scale of the financial commitment needed……………………………. https://www.cato.org/regulation/fall-2025/next-nuclear-renaissance#
What Ends the SMR Bubble?

In the up leg of any hype cycle, bad news is somehow massaged away.
The downleg of the SMR hype cycle should be epic.
By Leonard Hyman & William Tilles – Oct 22, 2025, https://oilprice.com/Alternative-Energy/Nuclear-Power/What-Ends-the-SMR-Bubble.html
- Analysts warn that small modular reactors (SMRs) are caught in a classic boom-and-bust pattern.
- Despite promises of faster, cheaper builds, early SMR projects in China, Russia, and Argentina have suffered cost overruns of 300–700%.
- With hundreds of competing SMR technologies and no standardization, the market risks fragmentation and inefficiency.
We think the concept of the Small Modular Reactor (SMR) as a solution to many of our future energy needs is in the midst of a major bubble or hype cycle. Think of the latter as an inverted “V”. In the up leg, investors feel great about prospects and profits, which are, they believe, soon on the way. In the down leg, investor disappointment sets in as earlier financial forecasts are seen as pure fiction, with reality being much worse. In a way, this is how free markets with imperfect information work. The question is: what triggers the down leg in the hype cycle for SMRs? Our answer is the year 2029.
Power supply forecasts, as our readers know, are made in three to five-year increments. We think 2029 is the forecast year in which energy planners acknowledge reality. The fleet of SMRs expected to be in service in the first half of the next decade (2030-2035) simply won’t be there. And we believe this will trigger the down leg in the hype cycle. That’s our thesis, simply stated, and we’ll discuss why in a moment.
First, it helps to understand that the SMR is a reactive technology, meaning that its designers are reacting to a real problem. New gigawatt-scale nuclear plants take too long to build, and they’re too expensive. The last big nuclear plant built in the US, Plant Vogtle, cost three times its original budget and took twice as long as expected to build. The new French reactor at Flamanville was more than 200% over budget, also with extensive delays. Not the sort of experience to trigger a nuclear Renaissance.
This situation is what the SMR industry is responding to, saying that with modular, factory-built components, we can do nuclear new-builds much faster, hopefully in three to four years. As an aside, we should point out that construction firms may be able to build faster, but they can’t be cheaper than gigawatt-scale reactors because they’re engaging in an exercise of reverse economies of scale. What does this mean?
Let’s discuss this in terms of cars, not power plants, for a moment. The soccer parent goes to the new car showroom and says they need a car that seats eight. They purchase a minivan for $40,000. The capital cost to move each passenger is $5,000 ($40,000 divided by 8). A thrifty person goes to the same dealership but insists on only spending $20,000 and drives away in a slightly used two-seater. A thrifty person saved half as much on the total capital cost. But their cost to move each passenger ($20,000 /2) was twice as high, $5,000 vs $10,000. If we substitute the term kilowatts for “cost to move each passenger,” this demonstrates the issue. Like the bigger minivan, the smaller two-seater has to have all the same components as the bigger vehicle, only tinier.
We assume a similar logic applies in building new nuclear plants. Our guess is that electricity from SMRs will be at least 30% more expensive than best-in-class (on a cost basis) gigawatt-scale reactors based on relative capital costs. But the overall units, because they’re tinier, will cost less per reactor than gigawatt-scale reactors.
But we don’t think the cost differential between SMRs and gigawatt scale reactors will make all that much difference, and won’t turn the hype cycle, at least not for a while, because early adopters of SMRs will be relatively price insensitive buyers like the military in extremely remote locales, and inside the fence industrial users like large chemical plants which require both electricity and steam, such as the Dow Chemical refinery in Baytown, Texas.
And here is where we have real concerns about SMRs. Consider the astonishing array of new competing technologies and the variety of sizes, all falling under the rubric of SMRs. A tiny SMR today is less than one megawatt, and a large one is 300 MWs. There are way too many different sizes and technologies, many extremely well-financed, for us to speculate about winners and losers at this point. But this looks like an awful lot of competitors for a finite market. However, there are certain definitive things we can say. First, all this variety ignores the advice of nuclear engineers who advocate construction of standardized designs in decent numbers in order to enjoy cost reduction benefits for the nuclear fleet as a whole. Second, it would take over 1300 SMRs (assuming each had a capacity of 100 MW) to make a 10% impact on US power-generating capacity. (Total US generating capacity was 1,326,000 MW at the end of 2024.) The likelihood of completing so many projects within a few years is low.
JP Morgan’s 2025 energy report discussed SMRs on a global basis. There are only three completed SMRs in the world, one in China and two in Russia, with a fourth under construction in Argentina. The report noted cost overruns of 300% for China’s project, 400% for Russia’s, and 700% for Argentina’s. All units promised 3-4 year build times. It all took twelve years. When perusing the articles on the finances of these facilities, one finds the following explanations: design and manufacturing immaturity, lengthy periods for verification of passive safety systems, supply chain limitations in an immature industry, cost overrun challenges in FOAK (first of a kind) units. Sound familiar?
Let’s return to our original point about hype cycles and what makes them turn. Markets are like tolerant parents in a room full of children. They may tolerate a lot, but there are certain things they won’t stand for. Right now, the market seems to be indifferent to reactor size, technology, or even economics. Which is another way of saying financing to the industry remains available on very easy terms. And as investors, we would probably continue to play this from the long side at least for the near-term.
But the one thing investors won’t tolerate is if new SMRs experience the lengthy construction delays and eye-watering cost increases that have plagued new gigawatt-scale reactors. This early evidence, albeit skimpy, of just three new facilities, is not encouraging. But we don’t think investors in the West will worry. Not yet. In the up leg of any hype cycle, bad news is somehow massaged away. So for us, 2029 is the year forecasters in the West begin to acknowledge the impact of disappointing SMR construction delays (probably similar to delays experienced in China and Russia) and that the new SMRs that energy buyers expected “in the early 2030s” won’t be there. But it gets worse. The industry will then realize that by pursuing SMRs they got the same intolerably long construction periods and all the huge cost overruns, but at far worse price points, thereby jeopardizing the entire commercial viability of SMRs. The downleg of the SMR hype cycle should be epic.
We will give the last word to noted energy expert, Vaclav Smil, who said this in response to a question about the impact of SMRs: “Call me or send me an email once you see such wonders built on schedule, on budget, and in aggregate capacities large enough to make a real difference.“ He added that he didn’t expect a call for ten or twenty years.
Capitalism Is Shoving AI Down Our Throats Because It Can’t Give Us What We Actually Want.
Caitlin Johnstone, Oct 26, 2025, https://www.caitlinjohnst.one/p/capitalism-is-shoving-ai-down-our?utm_source=post-email-title&publication_id=82124&post_id=177138322&utm_campaign=email-post-title&isFreemail=true&r=1ise1&triedRedirect=true&utm_medium=email
At some point capitalism lost the ability to give us new things that we need and started giving us new things we don’t need, and now it’s giving us new things we never needed and don’t even really want.
Nobody needs all this generative AI crap. We were doing fine with online search functions and the ability to write and make art for ourselves. Only the most shallow and vapid of individuals find any appeal in the idea of talking to a chatbot like a companion, consuming “art” generated by a computer program, or letting the technology of some plutocratic megacorporation do their thinking, researching and expressing for them.
The economy is now balancing on a giant bubble of a fledgeling industry that is already underperforming expectations and hitting points of diminishing returns on multiple fronts, all while being really bad for the environment. And it doesn’t improve anyone’s life in any meaningful way.
Nobody asked for this.
And it’s not like people aren’t asking for things; capitalism just doesn’t have the ability to give them the things they are asking for. World peace. Affordable housing. Good health. Fast and efficient public transportation systems. Solutions to the various environmental catastrophes that status quo human behavior is driving us toward. The ability to have our needs met without spending all our time at work. Care for the needful. General human thriving. These are not demands that a system driven by the pursuit of profit for its own sake can supply.
When capitalism first showed up it delivered plenty of new things which people had a need and a desire for that weren’t available under previous systems like feudalism. The greatly increased material abundance and explosions of scientific and technological innovation ushered in with the dawn of capitalism caused human quality of life to improve by leaps and bounds.
But now we’re at a point where that just isn’t happening anymore. Things have stagnated, and we’re starting to backslide. People are getting dumber, sicker, lonelier, and more and more miserable. And the profit-driven systems we live under have no answers, besides throwing increasingly shitbrained technology at us so we can distract ourselves from how fucked up everything has gotten.
We are being driven into dystopia and annihilation by systems of our own making. We’re meant to be the smartest species on earth, but we locked ourselves in our invention — a self-reinforcing labor camp that makes us miserable — and then we get all huffy when people dare to question if it’s the only way of doing things. Literally every other species is smarter than us. Amoebas are having a better time of it.
This will change when humanity replaces capitalism with something better, in the same way we replaced feudalism with the superior system of capitalism. I don’t know what that system is going to look like, but it’s going to have to involve a move from a model that is driven by competition to one that is driven by collaboration. That’s the only way humanity will be able to channel all its brilliance toward the immense project of overcoming all the obstacles we now face as a species, along with all terrestrial organisms.
Until then, all we can do is try to help awaken as many of our fellow humans as possible to the reality of our circumstances. Use every means at our disposal to teach people how dire our plight is, how deceived we’ve been by the propaganda and indoctrination of the empire we live under, how sorely change is needed, and that a better world is possible. Once we get enough eyes open, we’ll have the numbers to force things to change.
Mainers will not benefit from coastal rocket launch sites
Economic and oversight concerns make this a bad idea for our state.
I read with interest the Sept. 17 op-ed by Thom Moore, “Maine should vie to be the next US spaceport,” arguing for Maine to become a place where rocket launches occur regularly.
It’s not surprising that a retired NASA scientist who is not from Maine feels our state would be improved by toxic industrial activity of the sort Texas and Florida have to deal with regularly. Moore writes: “… a space industry could make beneficial contributions to Maine’s economy and to the national supply of viable launch sites.”
Let’s examine those claims.
Claims of benefit to Maine’s economy must be weighed against the harms to our traditional economy. Maine’s economy is highly dependent on commercial fishing on the one hand and tourism on the other. Even with the government shutdown, tourists are still flocking to Acadia National Park from all over the world. It’s a uniquely beautiful spot where one can witness the first rays of dawn light in the continental U.S.
Residents of nearby Steuben earlier this year rejected a bid to build a rocket launch site offshore of their village, citing the threat to environmental health of waters where food is harvested and also significant noise pollution. And as far as optics, who wants to see a rocket launch facility within sight of Acadia? Not locals.
Previously, Jonesport rejected a launch site after passing a moratorium to halt development while local residents had time to study the proposal. Which town will be next to say it does not want to hear or see rockets launching from its coast?
At present there is almost no regulatory oversight of such potentially harmful uses of Maine’s shoreline. Look what SpaceX has done to Boca Chica, Texas, over local objections: littered bird nesting grounds with debris from rocket explosions and prevented local residents from access to their beach.
“National supply of viable launch sites” is a backhand acknowledgement of the central role of the Space Force branch of the Pentagon in pushing for launch sites to be constructed. No rocket launch site would be financially viable without military spending, and the U.S. military plans to benefit from the investments of private industry as much as it can with so-called public-private partnerships.
At least two rocket firms in Maine have acknowledged they’ve already received funding from the U.S. Space Force: bluShift Aerospace in Brunswick and VALT Enterprizes in Presque Isle.
But when the Maine Space Corporation was established, legislators were told that its purpose was research and development for civilian and educational purposes. They were explicitly told by the bill’s sponsor that there would be no military use.
This is also what locals in Kodiak, Alaska, were told when a rocket launch site was built there more than 20 years ago. Now, the site has expanded to multiple launch facilities and is most often used for Israeli military satellites and Pentagon payloads. Personnel are brought into Kodiak to oversee these launches, and the only local jobs generated are for custodians and security guards.
Wealthy people looking to profit from using Maine’s natural resources is nothing new. The CMP corridor is being built through the North Woods — over the objections of a majority of Maine voters — in order to enrich CMP and Hydro Quebec.
As you and your neighbors struggle to fund schools and heat your homes amid soaring inflation, ask yourself who would really benefit from building a rocket launch site on the coast of Maine
Straight from the horses’ mouths: Nuclear is a dead end.
By Ben Kritz, October 2, 2025, https://www.manilatimes.net/2025/10/02/opinion/columns/straight-fromthe-horses-mouths-nuclear-is-a-dead-end/2193114
ONE of the most authoritative and anticipated reports about the nuclear energy sector is the annual World Nuclear Industry Status Report (WNISR), which for close to 20 years has tracked the progress, or lack thereof, of the nuclear industry. It is, at least in my opinion, a better source for detailed information on the nuclear sector than the annual reports of the International Atomic Energy Agency (IAEA), because while the IAEA does provide completely reliable and detailed information, it provides a bit less than does the WNISR, and has an obvious positive bias toward nuclear energy.
The WNISR by contrast is completely neutral; even the bit of commentary that prefaces this year’s 589 pages of data and status updates confines itself to simply acknowledging the current reality of nuclear policy and activity, and leaves it to the audience to draw their own conclusions.
There are a few pieces of good news for nuclear enthusiasts in the 2025 WNISR. Nuclear power generation rose to 2,677 terawatt-hours in 2024, and generation capacity reached 369.4 gigawatts (GW). Those are both record highs, but on the other hand, they are both less than 1 percent higher than the previous records, and so are really not overwhelming evidence of a growing sector. One indication of that is that nuclear’s share of generating capacity declined slightly (by less than 1 percent) year on year, and is now at 9.0 percent. That is only about half its historic peak of 17.5 percent in 1996.
Other factoids that might encourage nuclear proponents are that there are three countries building their first nuclear plants — Bangladesh, Egypt and Turkey — all of which are being constructed and largely financed by Russia’s Rosatom. The number of reactor startups was higher than the number of shutdowns in 2024. Seven plants were brought online — three in China, and one each in France, the United Arab Emirates, the United States and India, while four were closed, two in Canada, and one each in Russia and Taiwan. At the end of 2024, there were 409 reactors operating worldwide (that number has since gone down by one this year), which were the same number as at the end of 2023. The number of operating reactors peaked in 2002 with 438, operated in 32 countries; since then, the sector has slowly declined. There are only 31 countries as of now, and the number of reactor closures across the past 20-odd years has been slightly higher than the number of startups.
For example, the WNISR notes that from 2005 to 2024, there were 104 startups and 101 closures, which might seem like a modest gain. But any nuclear expansion is solely attributable to China; in that time period, there were 51 startups and no closures in China. In the rest of the world, there was a net decline of 48 in the number of operating reactors, with a corresponding decline in generating capacity of 27 GW.
China has big numbers in everything because China is very big; in its broader energy mix, nuclear power is at best an afterthought, and is declining even there. Nuclear’s share in the total energy mix in China fell for the third straight year in 2024, down to 4.5 percent. While nuclear capacity did increase by 3.5 GW from a year earlier, it was overwhelmed by the growth in solar capacity, which increased by 278 GW. In China, since 2010, the output of nuclear has increased by a factor of six. But on the other hand, the output of solar increased by a factor of more than 800, and wind by a factor of 20. Renewables’ share of the energy mix increased from 18.7 percent in 2010 to 33.7 percent in 2024, or in other words, outpaced nuclear by 7.5 times.
Prospects for growth
The simple answer is that there aren’t any; some incremental gains here and there may be possible, but the idea that nuclear is the go-to solution for decarbonization is not at all supported by real-world trends. The first problem is that existing nuclear power is quickly reaching the end of its useful life. The WNISR notes that the average age of the presently operating power reactors has been increasing since 1984 and stands at 32.4 years as of mid-2025. The average age at closure of the 28 reactors permanently shut down between 2020 and 2024 was 43.2 years. The nuclear industry is going to have to expend increasing effort and resources in senior care for its aging plants just to maintain the status quo of stagnation and gradual slow decline.
Investment figures bear that out. Over the past decade, the WNISR notes that nuclear investment has been essentially stagnant, although not nonexistent; in the same time period, investment in renewables has increased by 21 times.
Apart from the three newcomers (Egypt, Bangladesh and Turkey) that are actually building reactors, the WNISR identifies 12 others with prospects for nuclear power sometime in the future, four of which are in Africa. It may come as a discouraging surprise to our own Department of Energy and nuclear cheerleaders here that the Philippines is not even mentioned.
In fact, the name “Philippines” appears exactly once in the 589 pages of the report, on a chart listing countries that have abandoned or suspended reactor constructions since 1970. But to be fair, the recent passage of the Philippine Nuclear Safety Act and its subsequent creation of an actual regulating body are recent developments, so the 2026 WNISR will probably include it.
None of the other countries noted are even close to beginning construction, or even seriously considering it. In fact, the World Nuclear Association, which is definitely an optimistic source of information, in a Sept. 19 report concluded that only one additional country besides those already building reactors — Poland — is likely to join the nuclear energy community within the next 15 years.
The WNISR’s overall conclusion kind of says it all: “2024 has seen an unprecedented boost in solar and battery capacity expansion driven by continuous significant cost decline. As energy markets are rapidly evolving, there are no signs of vigorous nuclear construction and the slow decline of nuclear power’s role in electricity generation continues.”
The Philippines’ nuclear aspirations, and likely those of any other country anywhere else, are clearly swimming against the tide. That does not make nuclear development impossible, but it almost certainly means that any development that is achieved will have much less impact than anticipated. And, nuclear being what it is, that impact will cost more and take longer to achieve than expected.
The broad picture painted by the WNISR brings us back to the conclusion of the Cato Institute assessment I discussed in the first part of this column on Tuesday, and bear in mind this is coming from a deeply conservative source: “The problem is not so much that money will be wasted on large numbers of uneconomic facilities. Rather, it is the opportunity costs of the time and human resources that are consumed by nuclear power and not available to other, quicker, more cost-effective and less financially risky options. We appear now to be facing serious risks from climate change, and there will not be a second chance if we fail to tackle it because too many resources are being consumed by an option — new nuclear — that will not work.”
Amazon spills plan to nuke Washington…with X-Energy mini-reactors
COMMENT. At left -the picture of the as yet non-existent “small” nuclear project, to supply great steel towers -the so-called “cloud” of data.
The nuclear and AI industries abound with lies in their propaganda
Now they just need to get regulatory approval
Tobias Mann, The Register, Fri 17 Oct 2025
Despite technological and regulatory hurdles, Amazon remains convinced that small modular reactors (SMRs) are the answer to the cloud titan’s power woes.
Last fall, the house of Bezos announced a $500 million investment in SMR startup X-Energy. On Thursday, the e-tailer revealed that X-Energy’s Xe-100 SMR designs would eventually supply Washington State with “up to” 960 megawatts of clean energy.
“Eventually” is the key word here as construction isn’t expected to start until the end of the decade and the plants won’t begin operations until sometime in the 2030s.
The plan is to deploy the 80 megawatt reactors at a new facility called the Cascade Nuclear Energy Center outside Richland, Washington, in three phases, each totaling 320 megawatts of generative output. For context, xAI’s 200,000-GPU Colossus supercomputer uses roughly 300 megawatts of power when it is fully utilized.
Amazon notes that X-Energy’s SMRs should be smaller, faster to deploy, and cheaper to operate than conventional pressurized water reactors. This is a common argument in support of the miniaturized nuclear power plants, but it’s worth noting that the tech hasn’t actually been proven out. In fact, higher-than-expected operating costs have already doomed one early SMR project.
And that’s not the only challenge facing X-Energy. The company’s SMR tech has yet to receive Nuclear Regulatory Commission approval, which is required before construction of the reactor itself can begin. But that’s not stopping Amazon from sharing 3D renders of what the power plant might look like when complete………………………………………………………………………………………………
https://www.theregister.com/2025/10/17/amazon_nuke_washington/
The Troubling Data on Data Centers

Below is an extract from a pro nuclear article. It was rather subtly pro-nuclear. But I decided not to give its rather dubious pro nuclear arguments any publicity on this ste.
One example – the author praises the “cheapness” of France’s nationalised nuclear power, ignoring its downside of debt and climate-accelerated shutdowns.
Nuclear Is Here To Save AI. But What About Your Energy Bills? October 12, 2025, Brian Boyle, The Daily Upside
A nuclear boom is directly downstream from the AI boom, with $350 billion in nuclear spending in the US planned by 2050, per Bloomberg.
The artificial intelligence revolution is officially upon us. If the abrupt improvement in your co-worker’s email grammar didn’t tip you off, the drastic increase in your power bill is a hard-to-miss clue. (And if your bill hasn’t changed much yet, consider yourself lucky.)
As the massive, power-hungry data centers that power AI’s expansion come online, they’re competing for power with everyone else. That’s driving up energy bills for industry and consumers alike, while testing the limits of US energy production capacity and stressing an aging power grid.
Silicon Valley has a solution: nuclear energy. Big Tech is investing heavily in the long-shunned (in the US, at least) energy source to power its AI moment, mostly in the form of so-called small nuclear reactors (SMRs), the next-gen version of nuclear tech that can (theoretically) be mass-produced and strategically deployed. (For the uninitiated, it might be helpful to think of SMRs as gas generators on radioactive steroids.) Now, a nuclear boom is directly downstream from the AI boom: According to a recent Bloomberg Intelligence report, soaring power demand from AI will spur $350 billion in nuclear spending in the US by 2050.
The US government, which views dominance in the AI sphere as crucial to continued economic and geopolitical dominance around the globe, is entirely on board. In a rare instance of bipartisan consensus, both the current and previous administrations have moved fast to cut red tape, overhaul oversight processes, and pour capital into the resurgent nuclear industry.
“We’re in a very serious bind. We’ve already tapped out traditional oil and gas technologies. There’s an eight-, nine-year queue for diesel generators, the most expensive form of energy, and now also gas turbines,” Kevin Kong, founder and CEO of AI-driven nuclear compliance platform Everstar, told The Daily Upside. “Renewables are not dense enough … Data centers run 24/7, and are extremely power-dense. And so the only technology that’s left that was overlooked and under-invested in is nuclear.”
In other words, if we’re going to have an AI revolution, we’ll need plenty of nukes. But will the industry insulate Americans from rising energy bills? Maybe.
The Troubling Data on Data Centers
For years, experts had estimated energy demand growth in the years and decades to come based on banal drivers such as population growth, economic expansion and development of emerging economies, as well as the electrification of everything, including major industries like manufacturing and transportation. It would be predictable and hence manageable, they believed.
Then came ChatGPT. Now? Most estimates predict that global energy demand will nearly double by 2050. A recent report from the International Energy Agency (IEA) found that over 50% of that growth will be driven by AI expansion. For example, a ChatGPT query requires roughly 10 times the energy, on average, needed for a Google search. To put it in even starker perspective, the IEA estimates that a typical AI-focused data center consumes as much electricity as 100,000 homes, while the largest such data centers consume 20 times that amount.
According to a recent Goldman Sachs report, data center power demand is expected to increase 160% by 2030 alone, and meeting 60% of that demand will require new energy generation capacity. Meanwhile, a report produced by Lawrence Berkeley National Laboratory and published by the Department of Energy estimates that data centers will consume more than 12% of total US electricity by 2028, up from 4.4% in 2023.
The triple-digit growth figures are already having a triple-digit impact on those suddenly, and sometimes unwillingly, competing with data centers for electricity. According to a recent Bloomberg analysis of energy data, monthly electricity costs in areas near data centers are now 267% higher than just five years ago, at the dawn of the AI age (that compares with a cumulative overall inflation rate of about 25%).
“Without mitigation, the data centers sucking up all the load is going to make things really expensive for the rest of Americans,” said David Crane, chief executive officer of Generate Capital…………………………………………………………………………………………………..
One Bubble After Another: While SMRs are likely to deliver consistent energy supplies to massive data centers, a valuable proposition in its own right, not everyone is convinced it will be delivered cheaply.
According to data from Wood Mackenzie recently seen by the Financial Times, the “levelised cost of energy” for SMRs, or the cost for power that should be charged for the project to break even, will be around $182 per megawatt hour in 2030. That compares to $133 per megawatt-hour from traditional nuclear power plants, such as Vogtle, $126 for natural gas, and even less for wind and solar. https://www.thedailyupside.com/technology/artificial-intelligence/nuclear-is-here-to-save-ai-but-what-about-your-energy-bills/
Small reactors, big problems: the nuclear mirage behind AI’s energy hype
Enrique Dans, Medium.com, 12 Oct 25
In the debate over the energy infrastructure required for the rapid growth of AI, small (nuclear) modular reactors (SMEs)are being touted in some quarters as a reliable, dense and zero-carbon way to supply data centers and critical networks.
A seductive idea for industries looking to justify colossal investments, it also demands rigorous and critical scrutiny. After all, a nuclear reactor is a nuclear reactor, with inherent dangers, and multiplying the number of installations also multiplies the risk vectors. An SMR on a truck: what could possibly go wrong?
The promise of “safer”, “modular”, “quick to deploy” and “low carbon” energy doesn’t hold up in the face of history, economics, or risk analysis. Modular designs have been explored before, and they faced the same obstacles: uncontrollable costs, complex engineering, difficulties in scaling and operational problems. The simple truth is that small nuclear reactors can’t compete with renewables today. Instead, the arguments are based on political, financial and institutional motivations, fueled by a mentally ill person who hates renewables.
First, the technical and operational risks. A reactor, large or small, is based on fissile materials; radioactive, very hot and requiring complex cooling systems. There are no………………………………………………………….. (Subscribers only) https://medium.com/enrique-dans/small-reactors-big-problems-the-nuclear-mirage-behind-ais-energy-hype-77f93a3a4460
Peace is Possible – The Weaponization of Space with Bruce Gagnon.
Peace is Possible – The Weaponization of Space with Bruce Gagnon
West Hartford Community Interactive, 1 Oct 25
Joe Wasserman interviews Bruce Gagnon, Coordinator and co-founder of the Global Network Against Weapons & Nuclear Power in Space. https://www.youtube.com/watch?v=Y_ps6sJI1XM
US and investors gambling on unproven nuclear technology, warn experts

The US government and investors have made a $9bn gamble on small nuclear
reactors to power the AI boom and lower emissions — but experts warn the
technology could prove too costly to be viable.
Data compiled by the FT
shows that since 2019, government agencies including the energy and defence
departments have committed over $6bn to developers of small modular
reactors (SMRs) through awards, loans and cost sharing agreements. Private
investment has also soared, with over $3bn raised in the same timeframe.
The technology promises a one-stop solution to data centres’ power needs
by providing clean, reliable and cheap electricity for companies to train
and run their AI models. Investor enthusiasm has lifted the share prices
and valuations of companies with little or no revenues or operating
projects.
“There’s a lot of cheerleading happening, but the amount of
capital that you need to cross the finish line is huge,” said Chris
Gadomski, head of nuclear research at BloombergNEF, which estimates data
centre power needs will more than double by 2035. “What I see happening
with SMRs and data centres reminds me of the internet boom and bust of the
early 2000s.”
FT 5th Oct 2025, https://www.ft.com/content/8a18e722-3efa-404e-9f2a-709eed877f18
1 This Month
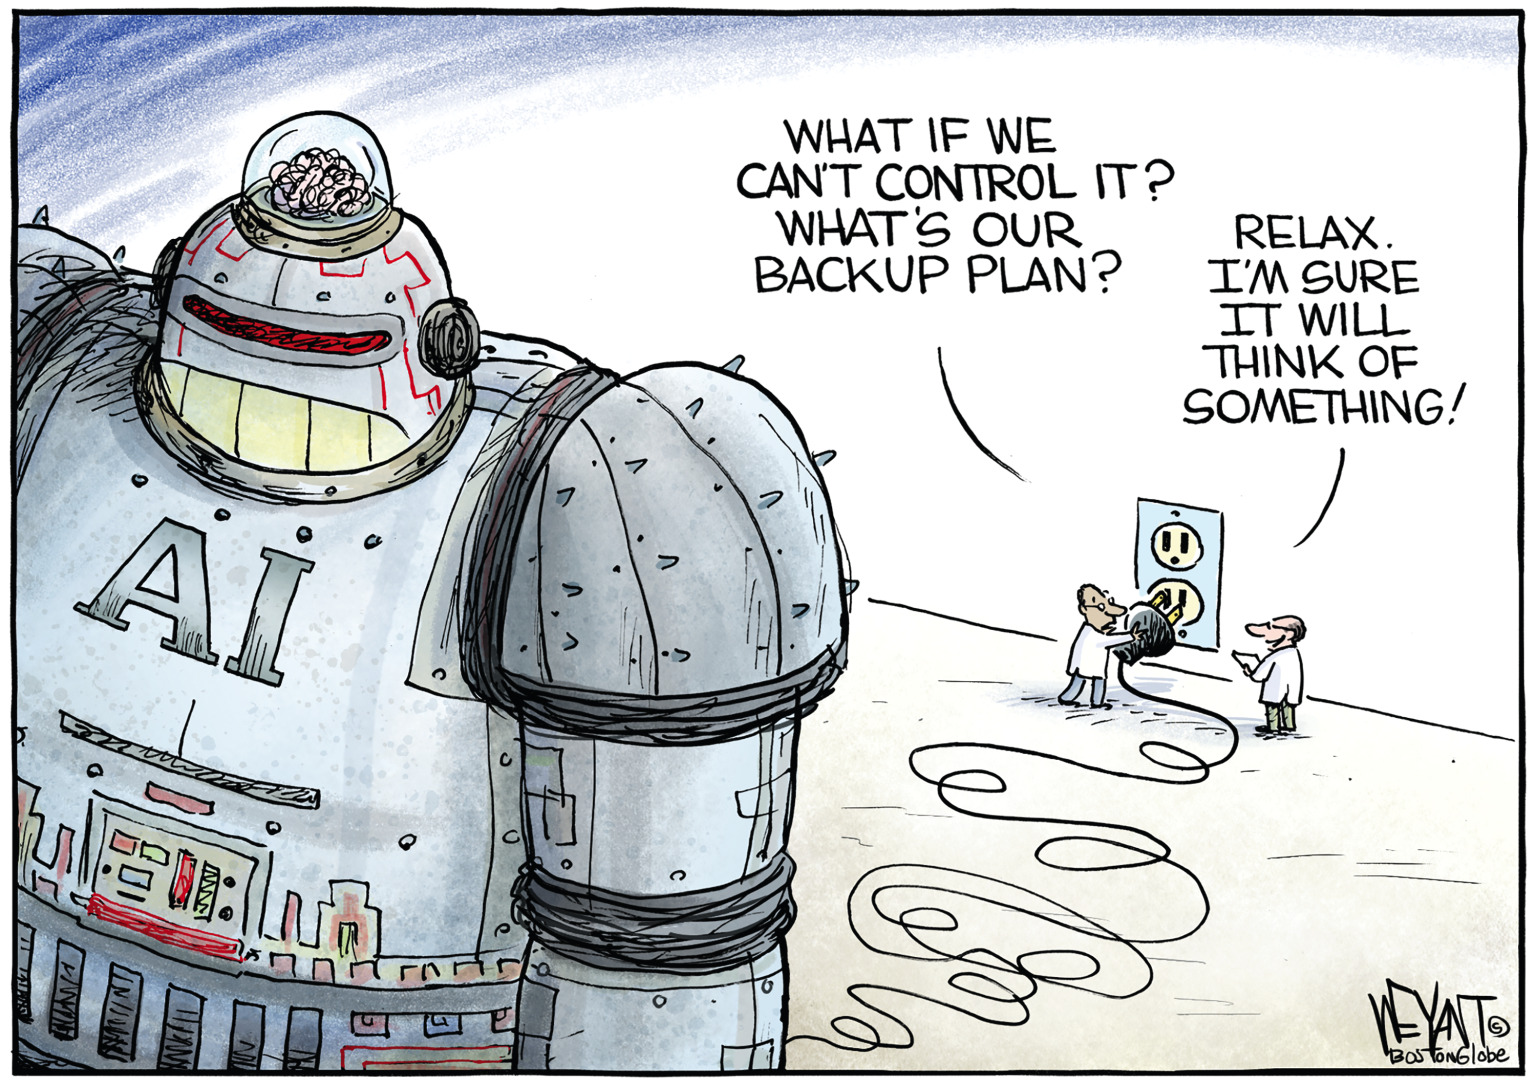
To see nuclear-related stories in greater depth and intensity – go to https://nuclearinformation.wordpress.com
-
Archives
- September 2026 (194)
- August 2026 (330)
- July 2026 (355)
- June 2026 (287)
- May 2026 (306)
- April 2026 (356)
- March 2026 (251)
- February 2026 (267)
- January 2026 (308)
- December 2025 (358)
- November 2025 (359)
- October 2025 (375)
-
Categories
- 1
- 1 NUCLEAR ISSUES
- business and costs
- climate change
- culture and arts
- ENERGY
- environment
- health
- history
- indigenous issues
- Legal
- marketing of nuclear
- media
- opposition to nuclear
- PERSONAL STORIES
- politics
- politics international
- Religion and ethics
- safety
- secrets,lies and civil liberties
- spinbuster
- technology
- Uranium
- wastes
- weapons and war
- Women
- 2 WORLD
- ACTION
- AFRICA
- Atrocities
- AUSTRALIA
- Christina's notes
- Christina's themes
- culture and arts
- Events
- Fuk 2022
- Fuk 2023
- Fukushima 2017
- Fukushima 2018
- fukushima 2019
- Fukushima 2020
- Fukushima 2021
- general
- global warming
- Humour (God we need it)
- Nuclear
- RARE EARTHS
- Reference
- resources – print
- Resources -audiovicual
- Weekly Newsletter
- World
- World Nuclear
- YouTube
-
RSS
Entries RSS
Comments RSS
 nuclear-news
